Your retirement spending won’t necessarily stay the same as you age. Understanding how expenses change can help you make better decisions about your FERS pension, Social Security, and TSP.
How much income will you need in retirement?
You’ve probably heard that you should plan to replace 80% of your salary. If you earn $100,000 a year, that means aiming for $80,000 in retirement.
But what if you’re only spending $65,000 of that salary today? And what if your spending changes as you grow older?
These are important questions that the traditional income replacement rule doesn’t answer.
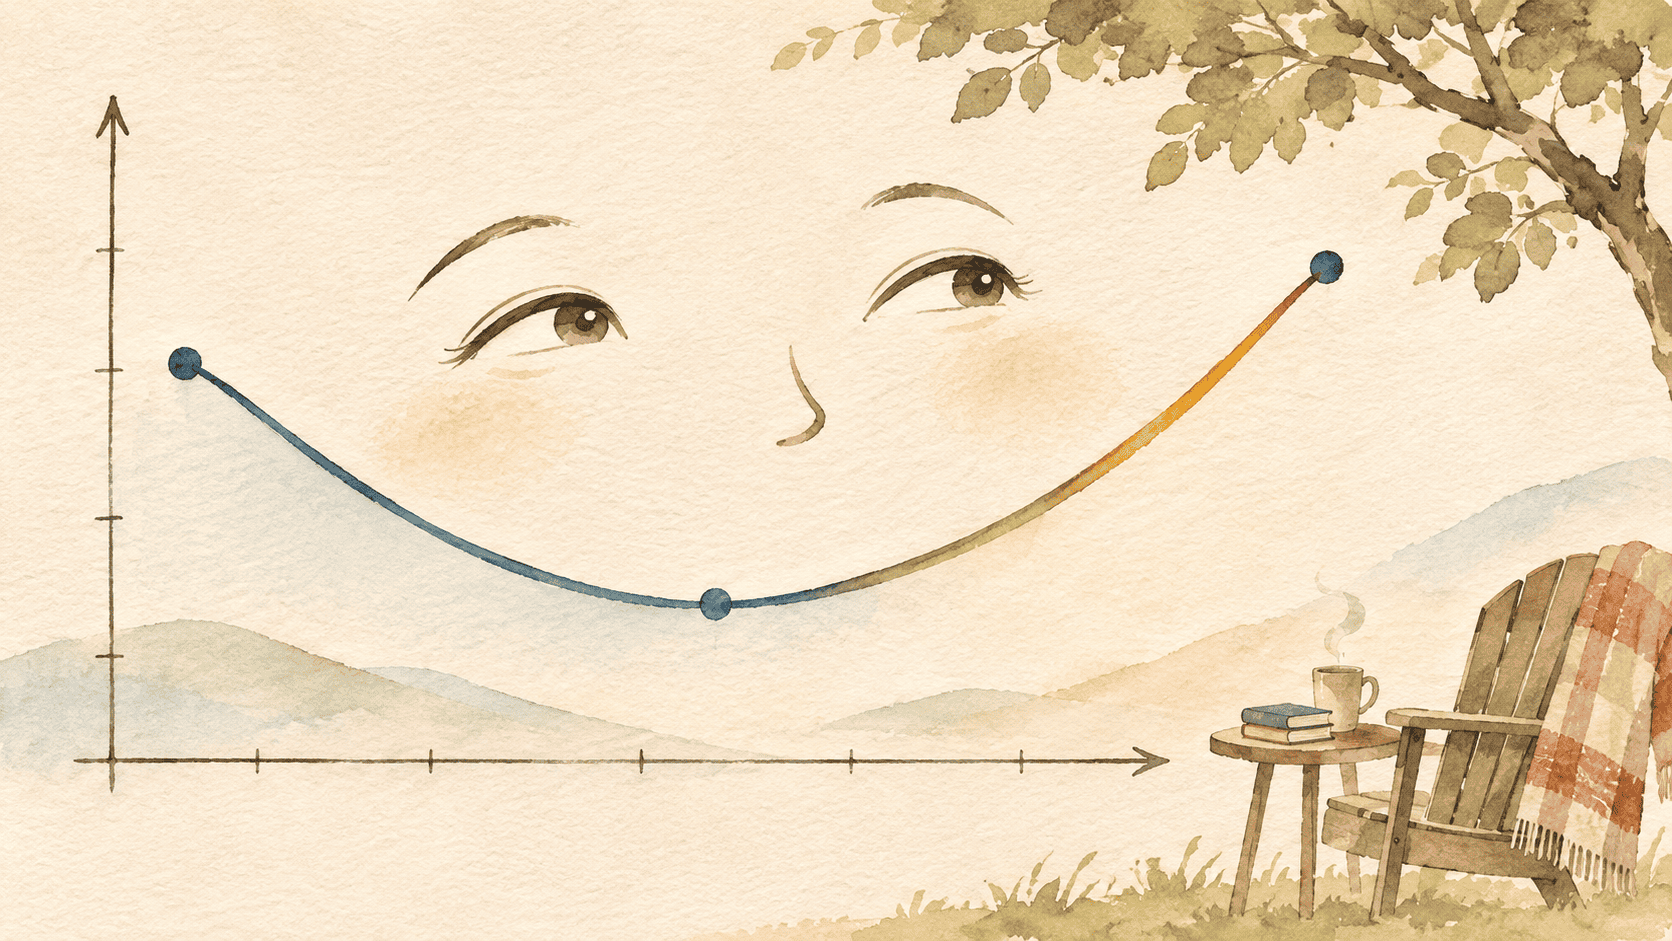
Research suggests that retirees often spend more in their early retirement years, less as they grow older, and sometimes more again toward the end of life.
Financial researchers call this pattern the retirement spending smile.
But recent research offers a more nuanced picture. The familiar smile isn’t inevitable, and the way your own expenses change may be quite different.
This has important implications for how you plan to use your FERS pension, Social Security, and TSP savings.
Why Replacing 80% of Your Salary May Be the Wrong Goal
Your salary isn’t the same as the amount your household consumes.
While you’re working, some of your paycheck goes toward Social Security and Medicare taxes. You may also contribute a significant portion to your TSP.
You might spend money commuting, buying work clothes, or eating lunch away from home.
Many of those expenses disappear or decline when you retire.
Consider a federal employee earning $120,000 who contributes 15% to the TSP.
That’s $18,000 a year going into retirement savings rather than household spending. Add payroll taxes and work-related expenses, and the employee may already be accustomed to living on considerably less than $120,000.
Of course, retirement also brings new expenses. You may travel more, pursue hobbies, or spend money on things you previously didn’t have time to enjoy.
So instead of asking how much salary you need to replace, consider a different question:
How much money will you actually spend in retirement, and how will that spending change over time?
This is the foundation of consumption-based retirement income planning.
What Is the Retirement Spending Smile?
Financial researcher David Blanchett explored how spending changes as retirees age in his 2014 study, Exploring the Retirement Consumption Puzzle.
His research found that inflation-adjusted spending tends to decline during retirement, even though the prices of goods and services generally rise.
He described a spending pattern commonly called the retirement spending smile.
The traditional explanation divides retirement into three phases.
The Go-Go Years: Approximately Ages 60–74
These are often the most active years of retirement.
You’re newly retired, your health may still be good, and you finally have time to travel, pursue hobbies, and enjoy experiences that were difficult to fit into your working life.
Discretionary expenses may be relatively high.
And there’s an important reason to consider spending more during these years: some experiences become more difficult as you age.
The Slow-Go Years: Approximately Ages 75–84
As retirees grow older, their spending preferences often change.
You may still travel, but less frequently. You might eat out less, drive fewer miles, or become less interested in expensive purchases.
These changes can reduce spending, even when you have the financial resources to maintain your former lifestyle.
The No-Go Years: Approximately Age 85 and Beyond
In later retirement, discretionary spending may continue to decline.
But healthcare and personal care expenses can increase. Some retirees need assistance with daily living, home healthcare, or residential care.
These costs can potentially push total spending upward again, forming the smile.
However, not everyone experiences this final increase.
In June 2026, Blanchett revisited his research in How Spending Evolves in Retirement: A Smile, a Smirk, or Something Else?
His updated findings suggest that retirees commonly reduce inflation-adjusted spending as they age. Some experience an eventual increase, while others continue spending less throughout retirement.
He described these different patterns as a spending smile and a spending smirk.
The lesson isn’t that everyone should follow a particular spending curve. It’s that retirement expenses change, and planning should reflect those changes.
A Better Way to Estimate Retirement Spending
Rather than assume your household will follow a spending smile, you can build a projection from the expenses you actually expect to have.
I favor separating expenses into four categories.
1. Essential Living Expenses
These are expenses you need to maintain your basic standard of living.
They include housing, utilities, groceries, property taxes, and essential insurance costs.
These expenses may change over time, but many will generally rise with inflation.
2. Discretionary Lifestyle Expenses
These are expenses that make retirement enjoyable but can be adjusted when necessary.
Travel, hobbies, entertainment, dining out, charitable giving, and gifts to family members might fall into this category.
Research suggests that these expenses often decline in inflation-adjusted terms as people grow older.
That doesn’t mean you should assume you’ll stop enjoying life at a certain age.
It simply means your interests, activities, and spending preferences may change.
3. Routine Healthcare Expenses
Healthcare deserves its own category because its costs may rise faster than general inflation.
For federal retirees, this includes FEHB premiums, Medicare premiums where applicable, prescriptions, copays, and other out-of-pocket costs.
A retirement plan might assume general inflation of 3% annually while projecting routine healthcare expenses to increase by 5% or 6%.
For example, $6,000 in annual healthcare costs growing at 5.5% would exceed $17,000 after 20 years, measured in future dollars.
That $6,000 is merely an illustration, not an estimate of what every federal retiree should expect to pay.
Actual healthcare expenses depend on your FEHB plan, Medicare enrollment, family coverage, health conditions, and other factors.
4. Potential Long-Term Care Expenses
Long-term care is different from ordinary healthcare.
A retiree might never require paid long-term care. Another might need several years of help with bathing, dressing, preparing meals, or other daily activities.
These expenses can be substantial.
And while FEHB provides valuable medical insurance coverage, it generally does not pay for ongoing custodial long-term care. Medicare generally doesn’t cover that care either.
Rather than assume that everyone suddenly incurs a large new expense at age 85, a better approach is to model long-term care as a separate financial risk.
A comprehensive plan can examine what happens if you require home-based assistance, assisted living, or nursing care for varying lengths of time.
This helps you prepare for a potentially expensive event without assuming it will inevitably happen.
What Could This Look Like in Dollars?
Consider a hypothetical federal retiree household beginning retirement at age 65.
We’ll start with three annual expenses:
- Essential living expenses, excluding healthcare: $55,000
- Discretionary lifestyle expenses: $40,000
- Routine healthcare expenses: $6,000
That’s $101,000 in initial annual spending.
Now let’s assume:
- Essential living expenses maintain their purchasing power.
- Discretionary spending declines 2% annually after inflation.
- Healthcare expenses increase 5.5% annually, while general inflation averages 3%.
Instead of adding an arbitrary healthcare expense at age 85, we’ll project these categories independently.
Here’s how the household’s spending might evolve, expressed in age-65 dollars:
| Expenses | Age 65 | Age 75 | Age 85 | Age 95 |
|---|---|---|---|---|
| Essential living | $55,000 | $55,000 | $55,000 | $55,000 |
| Discretionary | $40,000 | $32,683 | $26,704 | $21,819 |
| Routine healthcare | $6,000 | $7,626 | $9,693 | $12,320 |
| Total annual spending | $101,000 | $95,309 | $91,397 | $89,139 |
Hypothetical illustration in constant purchasing-power dollars. It excludes extraordinary long-term care expenses and assumes the spending trends continue throughout retirement. The inflation and spending assumptions are illustrative, not predictions for an individual household.
Notice something interesting.
Even though healthcare expenses rise faster than inflation, the household’s total inflation-adjusted spending continues to decline.
This is closer to a retirement spending smirk than a smile.
And that’s perfectly reasonable.
Now consider what happens if the household eventually requires several years of paid long-term care.
Its spending could rise sharply during those years, potentially creating the upward curve associated with the spending smile.
The key difference is that we haven’t assumed that increased spending must occur at a particular age.
We’ve allowed the underlying expenses and possible care needs to determine the outcome.
How Much Income Will You Need From Your TSP?
For federal employees, estimating expenses is only half the picture.
The other half is understanding how much income your federal benefits will provide.
Your FERS pension and Social Security can cover a meaningful portion of retirement spending.
The remaining amount must come from your TSP, IRAs, brokerage accounts, or other financial resources.
This difference is your retirement consumption gap.
Suppose our hypothetical household receives $65,000 annually from its FERS pension and Social Security.
For simplicity, we’ll assume this income maintains the same purchasing power throughout retirement.
| Age | Annual spending | Pension + Social Security | Needed from savings |
|---|---|---|---|
| 65 | $101,000 | $65,000 | $36,000 |
| 75 | $95,309 | $65,000 | $30,309 |
| 85 | $91,397 | $65,000 | $26,397 |
| 95 | $89,139 | $65,000 | $24,139 |
Illustrative spending gap in age-65 dollars. Actual pension and Social Security income will change over time, and the FERS COLA may not fully match inflation. Taxes must be included consistently when determining required withdrawals. Additional income taxes triggered by retirement account withdrawals may increase the gross amount that must be withdrawn.
This household needs substantially more income from savings during its earlier retirement years.
But actual federal retirement income planning involves additional complications.
Your FERS pension generally doesn’t receive cost-of-living adjustments before age 62, and later adjustments may be smaller than inflation.
Your Social Security benefits may begin several years after your pension.
If you’re eligible for the FERS annuity supplement, it generally ends at age 62.
Taxes can also change as you begin taking TSP withdrawals, claiming Social Security, or taking required minimum distributions.
All these changes must be coordinated with your spending needs.
How Should You Fund Those Changing Expenses?
Once you understand your consumption gap, you can begin designing a strategy to meet it.
Different retirement income approaches offer different advantages.
Build a Reliable Income Floor
One approach is to coordinate guaranteed lifetime income sources with essential living expenses.
Your FERS pension and Social Security may cover much of your household’s basic needs.
Other suitable income arrangements may help address any remaining shortfall.
Your TSP and other investments can then support discretionary spending and longer-term goals.
Use Flexible Withdrawal Guardrails
Another approach allows portfolio withdrawals to change based on investment performance and your remaining financial resources.
If markets decline substantially, you might temporarily reduce discretionary spending.
If your financial position improves, you may be able to spend more.
The important distinction is that discretionary spending can often be adjusted more easily than essential expenses.
Organize Investments Around Spending Needs
A time-segmented strategy, such as The Bucket Plan®, organizes assets according to when they’ll be needed.
Money required in the near term can be held in relatively stable, accessible investments.
Money intended for later years can be invested with a longer time horizon.
This can help you avoid relying entirely on the stock market to fund immediate spending, although no investment strategy eliminates market risk.
What About Sequence-of-Returns Risk?
There’s another important consideration.
If your spending is highest during your first years of retirement, you may also need larger portfolio withdrawals during a period when investment losses can be particularly damaging.
This is called sequence-of-returns risk.
A major market decline shortly after retirement, combined with ongoing withdrawals, can leave less money invested to participate in a recovery.
That’s why we shouldn’t automatically assume that spending more early in retirement is safe just because future expenses may decline.
The plan should also test unfavorable market conditions, unexpectedly high inflation, changes in household income, and potential long-term care expenses.
The goal is to enjoy your retirement while maintaining the financial resources you’ll need later.
The Best Retirement Spending Plan Is Your Own
The retirement spending smile offers an important lesson: Your financial needs are unlikely to remain identical throughout retirement.
But the research also reminds us that there is no single spending pattern that fits everyone.
Some retirees travel extensively into their 80s. Others prefer a quieter lifestyle much earlier. Some face substantial healthcare or long-term care expenses, while others do not.
A thoughtful retirement income plan should reflect how you expect to live, not force your life into a predetermined spending curve.
For federal employees, that means coordinating your FERS pension, Social Security, TSP, taxes, healthcare coverage, and investment strategy around your actual spending needs.
At Better Federal Retirement™, we help federal employees bring these moving parts together into a coordinated, comprehensive retirement income plan.
Because the goal isn’t simply to make your money last.
It’s to make good use of your money throughout retirement, while protecting the financial security you’ll need along the way.
Better Planning. Better Investing. Better Retirement.
We’ll walk through your situation, answer your questions, and help you understand how health-aware planning can support a better federal retirement—on your terms.
Sources & References
The following research and government resources provide additional information about retirement spending patterns, healthcare inflation, federal retirement benefits, and long-term care.
-
Blanchett, David M. (2014).
Exploring the Retirement Consumption Puzzle.
Journal of Financial Planning, 27(5), 34–42.
Read the original research. -
Blanchett, David M. (2026).
How Spending Evolves in Retirement: A Smile, a Smirk, or Something Else?
Financial Planning Review, 9(2), e70032.
Read the updated research. -
Centers for Medicare & Medicaid Services (CMS).
National Health Expenditure Fact Sheet and Projections, 2025–2034.
Includes projections of national healthcare spending and out-of-pocket expenditure growth.
View CMS projections. -
U.S. Office of Personnel Management (OPM).
How Is the Cost-of-Living Adjustment (COLA) Determined?
Explains FERS and CSRS cost-of-living adjustment calculations and eligibility.
Read OPM guidance. -
U.S. Office of Personnel Management (OPM).
Will the FERS Annuity Supplement Continue After Age 62?
Explains the termination of the FERS annuity supplement regardless of Social Security claiming age.
Read OPM guidance. -
Medicare.gov.
Long-Term Care Coverage.
Explains the distinction between medical care and custodial long-term care, including services Medicare does not cover.
Read Medicare coverage guidance. -
U.S. Office of Personnel Management (OPM).
Federal Long Term Care Insurance Program.
Information about long-term care and the separate federal insurance program.
View OPM long-term care information.
Important: The financial examples in this article are hypothetical and are intended for educational purposes. They do not represent a forecast, guaranteed result, or personalized financial advice. Healthcare inflation, household spending, investment performance, and benefit payments will vary.

Leave a Comment